

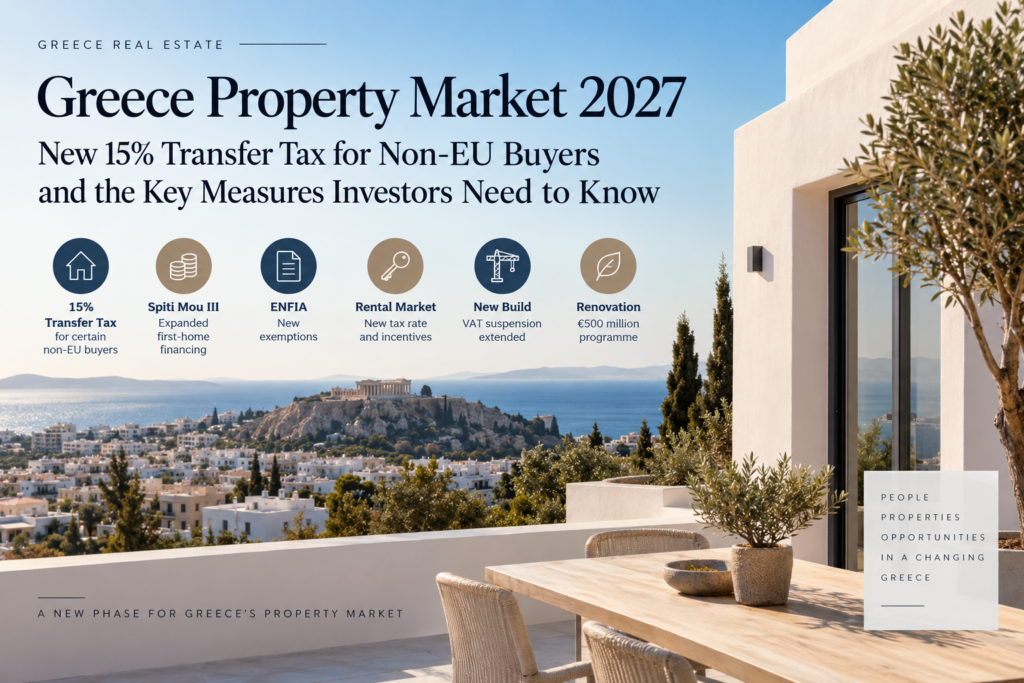
Greece property transfer tax 2027 changes are set to reshape part of the Greek real estate market, particularly for certain non-EU residential property buyers. Following the measures announced by the Greek government at the 90th Thessaloniki International Fair, foreign investors need to carefully assess how the new tax framework could affect the total cost of acquiring property in Greece.
The Greek property market is entering a new phase in 2027 following a package of housing and tax measures announced by the Greek government at the 90th Thessaloniki International Fair and subsequently detailed by the economic policy team.
The most significant development for international property investors is the announced increase in the property transfer tax on residential property purchases by certain non-EU nationals, from the current basic rate of 3% to 15%.
At the same time, the government has announced further measures affecting property taxation, first-home financing, vacant properties, new developments, short-term rentals and long-term residential investment.
For foreign buyers considering a property acquisition in Greece, particularly those from countries outside the European Union, these changes could materially affect the total cost and expected return of an investment.
The most significant measure for international investors is the proposed increase in the property transfer tax from 3% to 15% for residential properties acquired by certain nationals of third countries outside the European Union.
Under the current system, the basic property transfer tax is 3%.
The new measure would therefore represent a substantial increase in the acquisition cost of a residential property.
At a 3% transfer tax rate:
€300,000 × 3% = €9,000
At a 15% transfer tax rate:
€300,000 × 15% = €45,000
The difference is:
€36,000 in additional transfer tax.
For a residential property with a taxable value of €500,000, the difference between a 3% and a 15% rate would reach €60,000.
For investors, this means that the new measure could have a direct impact not only on the initial purchase budget but also on the overall return on investment.
Τhe Greece property transfer tax 2027 framework could therefore have a significant impact on the acquisition cost for certain non-EU residential property buyers.
This point requires particular attention.
The government announcement refers specifically to buyers from third countries outside the European Union.
However, it should not be assumed that every non-EU national will automatically fall within the 15% regime.
The final legislation will need to clarify the exact categories of buyers that will be subject to the increased rate, as well as any exemptions based on residence status, long-term residence rights, special immigration status or other legal criteria.
Until the legislation is enacted, the buyer’s nationality alone should not be treated as sufficient to determine the applicable tax rate.
The government announcement refers specifically to residential properties.
This distinction is important.
At this stage, investors should not assume that the increased 15% rate will necessarily apply in the same way to commercial real estate, land plots, development projects or other categories of property.
The final legislation will therefore be critical for investors considering alternative real estate structures or asset classes.
According to the government’s official explanation, the objective is to reduce part of the demand for residential property coming from third-country buyers and, as a result, ease pressure on housing prices.
This represents an important shift in Greek housing policy.
For many years, Greece actively encouraged international real estate investment.
The new measure introduces a clear tax disincentive aimed at a specific part of foreign demand in the residential market.
The effect is likely to vary substantially between locations.
Areas with strong international demand — including parts of Athens, the Athens Riviera, Piraeus, Thessaloniki and certain tourism-driven markets — may be more exposed to the impact of the new tax.
The distinction between immigration rules and property taxation becomes particularly important.
Eligibility for a Greek residence permit through investment and the tax treatment of the property purchase are two separate legal questions.
A buyer may qualify for a residence permit under the applicable immigration rules while still being subject to a particular property transfer tax regime.
For this reason, investors should not assume that Golden Visa eligibility automatically determines whether the 3% or 15% transfer tax will apply.
Once the legislation is enacted, both the buyer’s immigration status and tax position will need to be reviewed before calculating the final acquisition cost.
The Greece property transfer tax 2027 changes therefore require Golden Visa investors to assess the tax consequences of a property acquisition separately from the immigration requirements of the investment programme.
Investors considering residency through property investment may also consult our updated guide to the Greek Golden Visa framework and investment requirements.
A proposed increase from 3% to 15% naturally raises the question of whether non-EU investors should accelerate transactions planned for late 2026.
However, this requires caution.
The government announcement does not yet establish the detailed transitional rules that will determine which transactions fall under the old regime and which fall under the new one.
For example, the final legislation will need to clarify the treatment of transactions where:
Therefore, investors planning transactions around the end of 2026 should not rely solely on the announcement. The final legislation and its transitional provisions will need to be reviewed before deciding whether the timing of the acquisition can affect the applicable tax.
Foreign companies considering a direct acquisition or investment through a Greek entity should also review our complete guide to real estate investment in Greece, covering acquisition procedures, ownership structures and ongoing tax obligations.
The government has also announced the new “Spiti Mou III” programme, with a total budget of approximately €2 billion.
The new programme is expected to expand access to subsidised first-home financing.
Compared with the previous programme, the announced changes include:
The programme is expected to begin in early 2027.
From a market perspective, this could increase domestic demand, particularly in the segment of residential properties valued up to €300,000.
The government is therefore simultaneously attempting to reduce a portion of foreign demand while supporting domestic first-home buyers.
Further changes are expected to apply to the Greek annual property tax, known as ENFIA.
The government has announced an exemption for qualifying main residences located in smaller settlements.
The announced framework refers to settlements with populations of up to 2,000 residents, or up to 2,200 residents in Western Macedonia, subject to additional conditions.
Importantly, the exemption is not expected to apply automatically to every property in a small settlement.
The government’s detailed announcement refers to conditions including:
The final legislation will determine the precise eligibility requirements.
The new package also includes a new 25% intermediate tax rate for rental income.
This is intended to reduce the tax burden for landlords whose income would otherwise move directly into the higher 35% bracket.
For property owners, the measure may improve the after-tax return from long-term rental activity.
The actual benefit will depend on each taxpayer’s total annual rental income.
The government also intends to extend tax incentives for previously vacant properties that are brought back into the long-term rental market.
The policy objective is clear: to increase the number of homes available for long-term residential use.
For owners of vacant properties, the tax treatment may therefore become an important factor when deciding whether to keep a property unused or place it on the rental market.
The government has also announced an extension of the VAT suspension applicable to qualifying new buildings.
The continuation of this regime remains important for both developers and buyers of newly constructed property.
Where the suspension applies, it prevents the transaction from being subject to the 24% VAT regime that could otherwise apply to qualifying new-build sales.
This measure continues to support construction activity and the supply of new residential property.
Restrictions on new short-term rental registrations are also expected to continue in certain areas of Athens and Thessaloniki.
For investors, this has a practical consequence.
A buyer considering a property primarily for Airbnb or other short-term rental use should no longer assess the investment only on projected nightly rates and occupancy.
Before purchasing the property, it is increasingly important to verify whether the specific property can legally be registered and operated as a short-term rental under the rules in force at the time.
The government has also announced a new renovation programme with a budget of approximately €500 million, aimed at upgrading older residential properties, including moderate energy-efficiency improvements.
The measure is intended to bring older and currently underused housing stock back into productive use.
This could be particularly relevant in cities with a high number of older apartments that require renovation before returning to the residential market.
Another measure of particular interest to developers and institutional investors is the proposed tax incentive for build-to-rent projects.
The concept involves constructing residential properties specifically for long-term rental rather than immediate resale.
If the final tax framework is sufficiently attractive, this could create a new investment segment in Greece, particularly for professional investors seeking stable long-term rental income.
The detailed tax conditions and eligibility requirements will need to be assessed once the relevant legislation is published.
The new policy package intervenes on both sides of the housing market.
On the supply side, the government aims to:
On the demand side, it aims to:
These measures are unlikely to have the same effect across all areas and price categories.
In locations with strong third-country investor demand, the higher acquisition tax could reduce demand or increase buyers’ negotiating pressure on sale prices.
In the first-home market, however, the expansion of subsidised financing could maintain or even increase demand for eligible properties.
It would therefore be premature to conclude that the measures will automatically result in either a general increase or decrease in Greek property prices.
The impact is more likely to differ by location, property type, price range and buyer profile.
Foreign buyers should increasingly treat tax due diligence as part of the acquisition process rather than as a formality after the purchase has already been agreed.
Before signing a transaction, investors should review:
For transactions expected to complete around the end of 2026 or beginning of 2027, the transitional provisions of the new legislation may become particularly important.
2027 is expected to bring significant changes to the Greek property market.
The most striking measure is the announced increase in the property transfer tax from 3% to 15% for certain non-EU buyers acquiring residential property in Greece.
For affected investors, this could materially increase the cost of a property acquisition and alter investment returns.
At the same time, Greece is introducing or extending measures designed to support first-home buyers, increase housing supply, encourage long-term rentals and promote the renovation and construction of residential property.
The key point, however, is that several of these measures are currently based on government announcements and official policy details rather than completed legislation.
The final tax treatment, exemptions, effective dates and transitional provisions should therefore be confirmed once the relevant legislation is enacted and published.
For international investors, the Greece property transfer tax 2027 changes make careful tax planning before a property acquisition more important than ever.
This article is for general informational purposes and reflects the official government announcements available as of 8 September 2026. It does not constitute personalised tax, legal or investment advice.